Syria's crop doubles to 954,000 tonnes — and the oil still only feeds itself
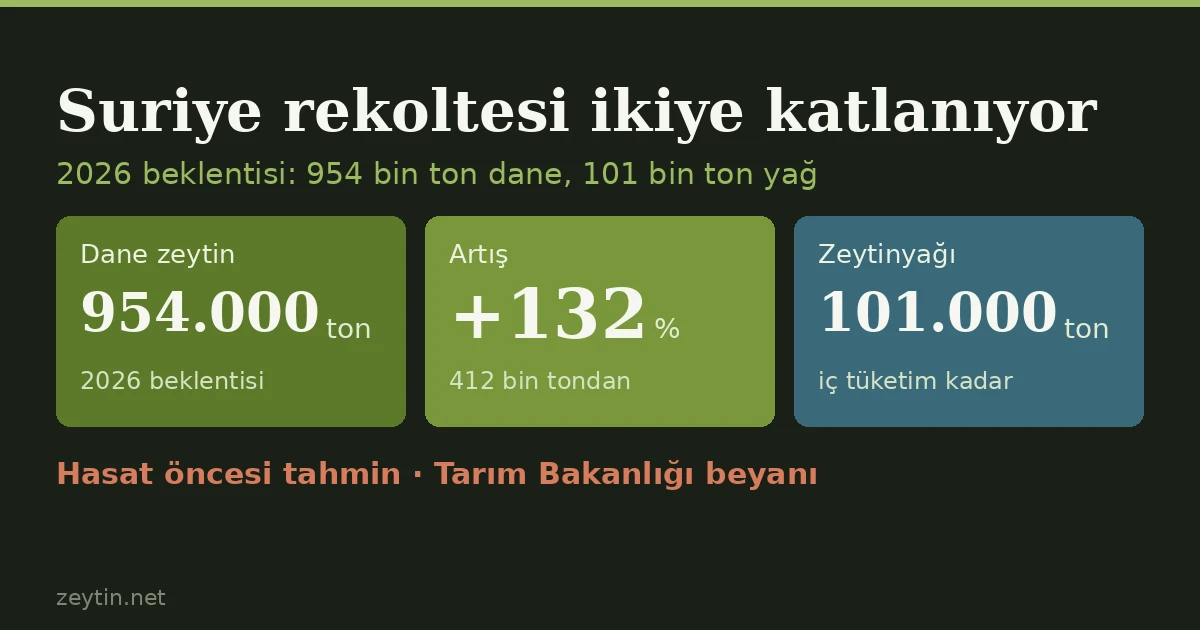
Syria's Ministry of Agriculture expects 954,000 tonnes of olives in 2026, up from 412,000 last season. The 101,000 tonnes of oil that implies barely covers domestic consumption — a doubled crop that still produces no export surplus.
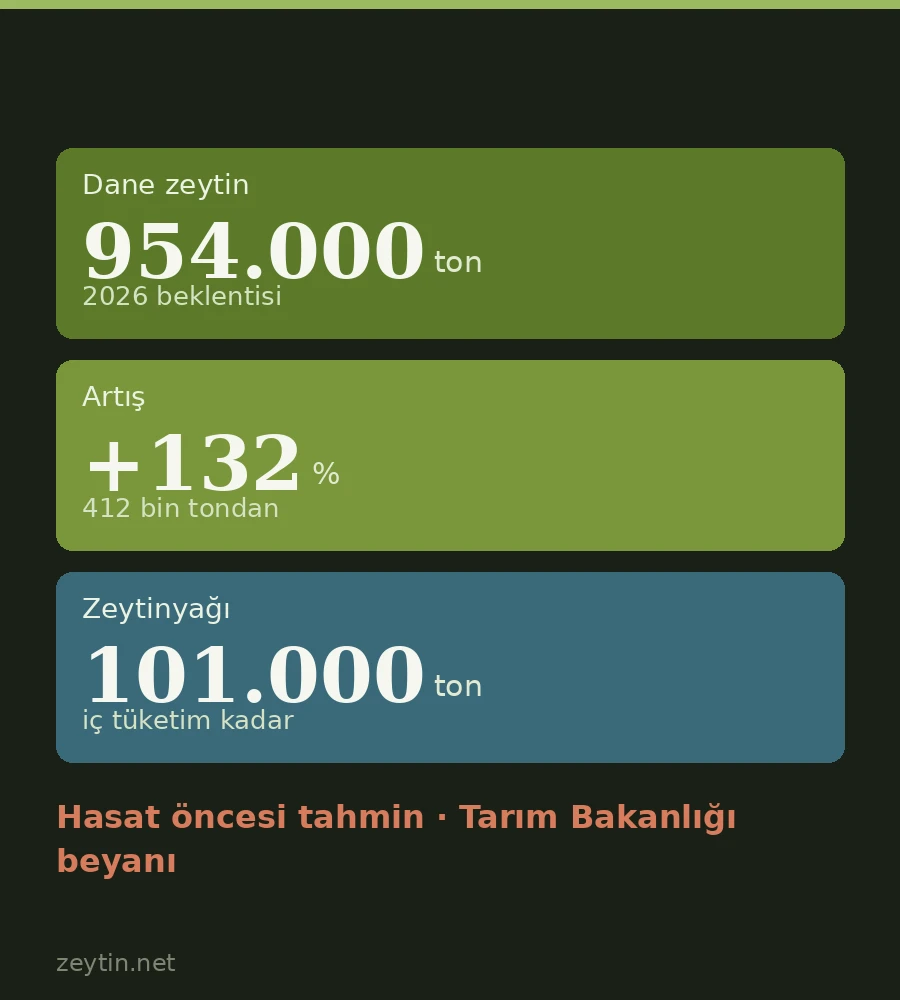
The Olive Office at Syria's Ministry of Agriculture published its 2026 season forecast on 21 September: 954,000 tonnes of olives. Last season the crop came in at 412,000 tonnes. That is more than a doubling in a single year.
The number
| Season | Olives |
|---|---|
| 2025 (actual) | 412,000 t |
| 2026 (forecast) | 954,000 t |
| Change | +132% |
The ministry also gave the split: 20% of the harvest goes to the table (191,000 t) and 80% to the mill (763,000 t). The oil expected from the milling share is 101,000 tonnes.
The production base is not small: roughly 101 million olive trees across 677,725 hectares. The ratio between those two figures works out to about 149 trees per hectare — the density of traditional, largely rainfed groves, not the intensive plantings that have redrawn the production map in Spain and Portugal over the past two decades.
Province by province
| Province | Olives |
|---|---|
| Aleppo | 226,300 t |
| Idlib | 156,800 t |
| Tartous | 127,800 t |
| Latakia | 121,100 t |
| Hama | 100,800 t |
The top five provinces together account for 732,800 tonnes, or 77% of the expected crop. Aleppo alone is close to a quarter of the national total. The list also maps Syrian olive growing: the northwest (Aleppo, Idlib), the coastal strip (Tartous, Latakia), and Hama inland.
Where the jump comes from
The ministry described last season's fall as more than 45% and attributed it to adverse climate conditions. The 2026 rebound is the natural counterpart: a tree that carries a light crop recovers the following year.
The same swing is visible from the opposite direction in the western Mediterranean this season. Tunisia is going from 500,000 to 300,000 tonnes, and there too the stated cause is alternate bearing. The opposite-phase pattern we have written about includes Syria: one end of the basin falls while the other rises.
⚠ Alternate bearing does not explain everything on its own. Climate was part of last season's decline, and when temperature thresholds are crossed and drought persists, the amplitude of the swing widens. We covered that widening separately in climate change and the olive.
What happened last season
To see why the 2026 number carries news value, it helps to look at 2025. The oil expected from that season's 412,000 tonnes of fruit was around 65,000 tonnes — noticeably below what the country consumes in a year.
The consequences of that situation in olive oil are well established: domestic prices rise, exports are restricted by administrative decision, and the restriction in turn pushes product towards unrecorded channels. Syria has run through exactly that sequence before — an export ban followed the collapse in production expectations, and permits for specific tonnages loosened it again once the outlook improved.
Which is why the 954,000-tonne forecast is, for Syria, less an export story than a normalisation story. What the market will actually watch is not the production figure itself but whether the export regime changes behind it.
The real question: who is 101,000 tonnes for?
The International Olive Council estimates Syrian domestic consumption at around 100,000 tonnes a year, roughly 2.6 kilograms per person. So even with the crop doubling, the 101,000 tonnes of oil now expected barely covers what the country itself consumes.
That sentence holds Syria's chronic position in olive oil. A good year does not mean an exportable year; it means a year without domestic shortage. In low-crop periods exports were restricted by administrative decision, and in later periods loosened again through quota permits. The 2026 figure gives grounds for relaxing those restrictions — but it does not create abundance.
It is worth holding the two sides of this together. By trees and by area, Syria is one of the larger olive countries of the Mediterranean; 101 million trees is a serious production base by any measure. By oil that actually reaches a market beyond its own borders, it is close to invisible. The gap between those two facts is the whole story, and a single good season does not close it.
What it means for Türkiye
1. Not a competitor in oil. A producer that barely covers its own consumption does not appear as a seller in the bulk olive oil market. The tanks Turkish exporters compete for are filled from Spain, Tunisia and Greece — not from Syria. Nothing in this forecast changes that for the coming season.
2. Table olives are a different matter. A volume of 191,000 tonnes of table olives is not a small number, and table olives are not bound by the same hard domestic ceiling as oil. Two thirds of Türkiye's olive exports are table olives, and the chance of meeting Syrian product in regional markets such as Iraq and the Gulf is higher than it is in oil.
3. The supply picture is getting more crowded. Tunisia is shrinking, Algeria is expecting a record, Syria is recovering. Taken one by one these are small movements; added together they form a floor that pulls price expectations down rather than up.
Reading it carefully
⚠ 954,000 tonnes is a pre-harvest estimate. We have written separately about when a crop estimate becomes final; the number moves in both directions as picking progresses.
⚠ Olives and olive oil are not the same thing. 954,000 tonnes of fruit, 101,000 tonnes of oil. Confusing the two is as common an error as mistaking exchange volume for the harvest.
⚠ The yield assumption is not stated. 101,000 tonnes of oil from 763,000 tonnes of milling fruit implies an extraction rate of 13.2%. Last season's pairing of 412,000 tonnes of fruit with roughly 65,000 tonnes of oil pointed to a higher ratio. The ministry did not explain the assumption linking the two figures, which makes the oil number more volatile than the fruit number.
⚠ The figure is the ministry's own declaration. It is not an independent field measurement, nor has it been confirmed by an international body.
One rating per visitor; you can change yours at any time. Ratings are real reader votes — no seeded or default scores.
Related
 Article
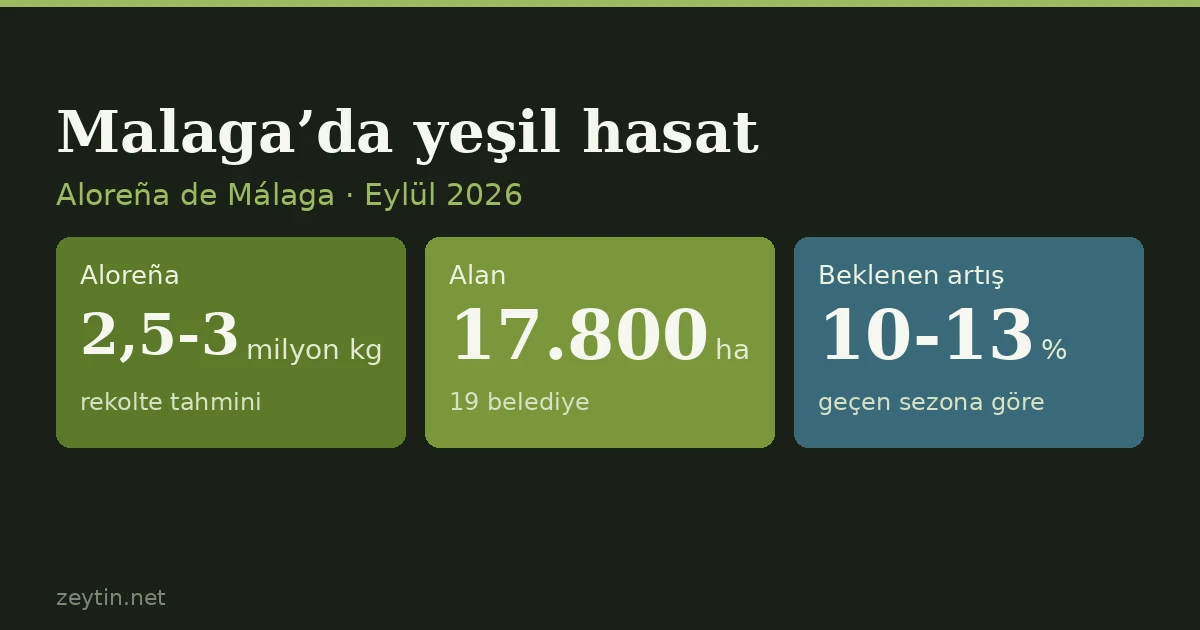
Green olive harvest begins in Málaga: 2.5 to 3 million kilos expected for Aloreña
Table olive harvesting has begun in Spain's Málaga province with better prospects after years of drought. The protected-origin Aloreña de Málaga is expected to yield 2.5 to 3 million kilos, and trees are heavily laden with Hojiblanca, which supplies more than 90 per cent of the province's table olives. September heat, however, is shrivelling fruit on rain-fed land.
 Article
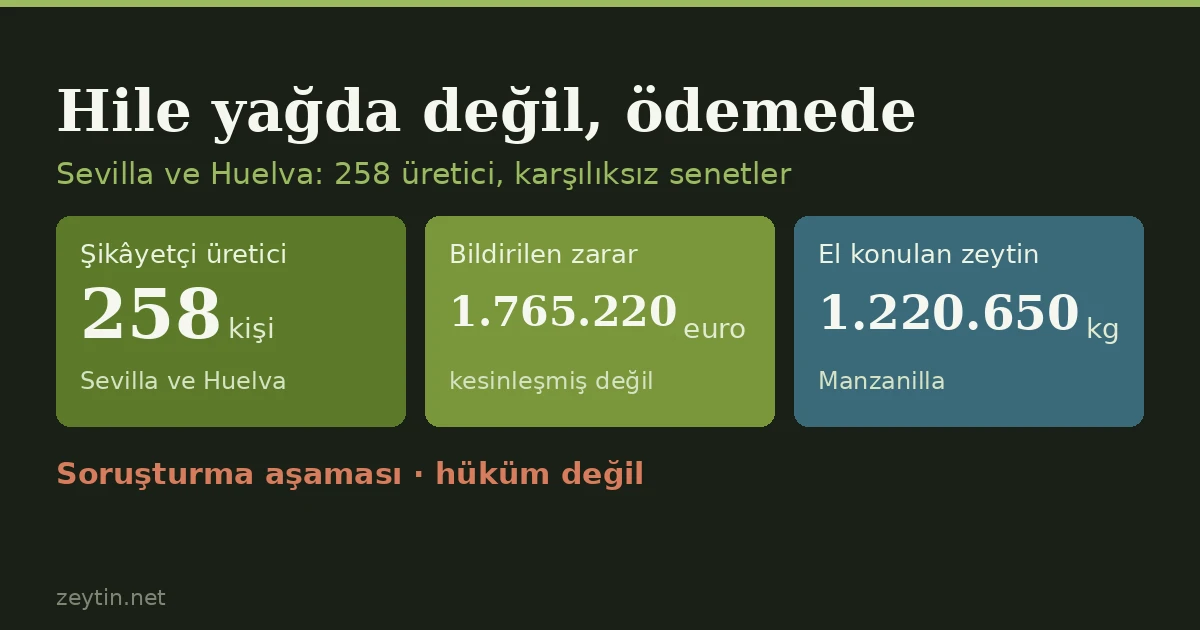
258 growers, €1.77 million: in Spain the fraud was not in the oil, it was in the payment
Spain's Guardia Civil has detained a table olive trader accused of defrauding 258 growers in Seville and Huelva of €1,765,220. The olives were real and the sales were real; the money never reached the producers. Investigators seized 1,220,650 kilos of Manzanilla olives.
 Article
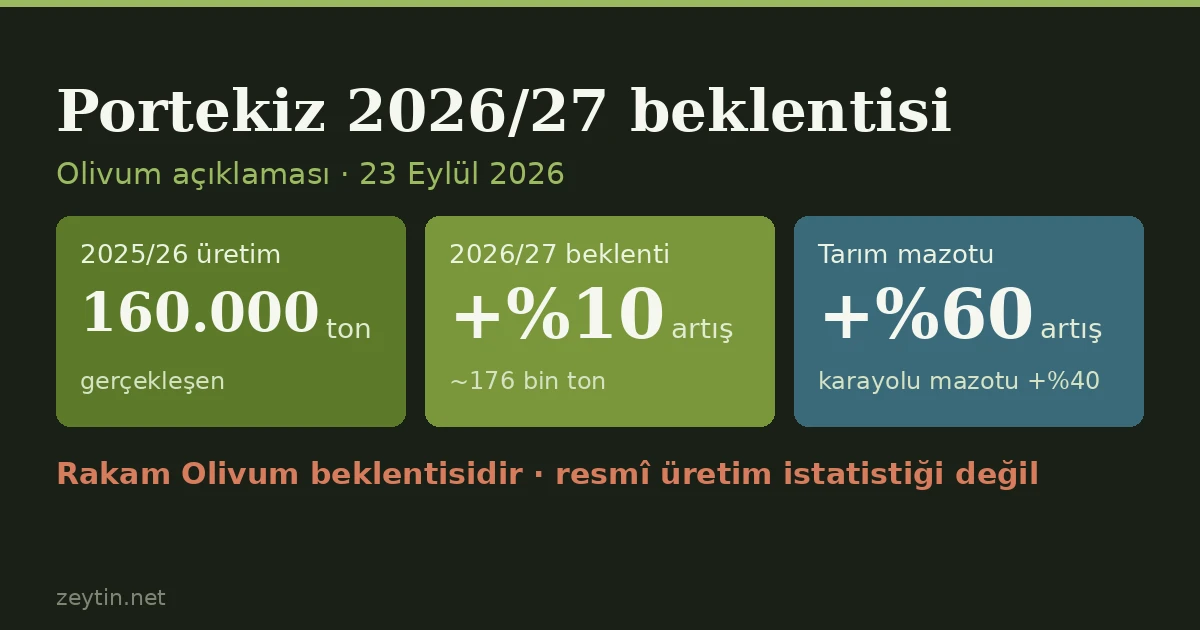
Portugal heads back to 177,000 tonnes: output up 10%, farm diesel up 60%
Portugal's olive association Olivum expects production to rise by about 10% in 2026/27 — a return from 160,000 tonnes to the 177,000 of two years ago. The same statement records a 60% rise in the price of agricultural diesel.
 Article
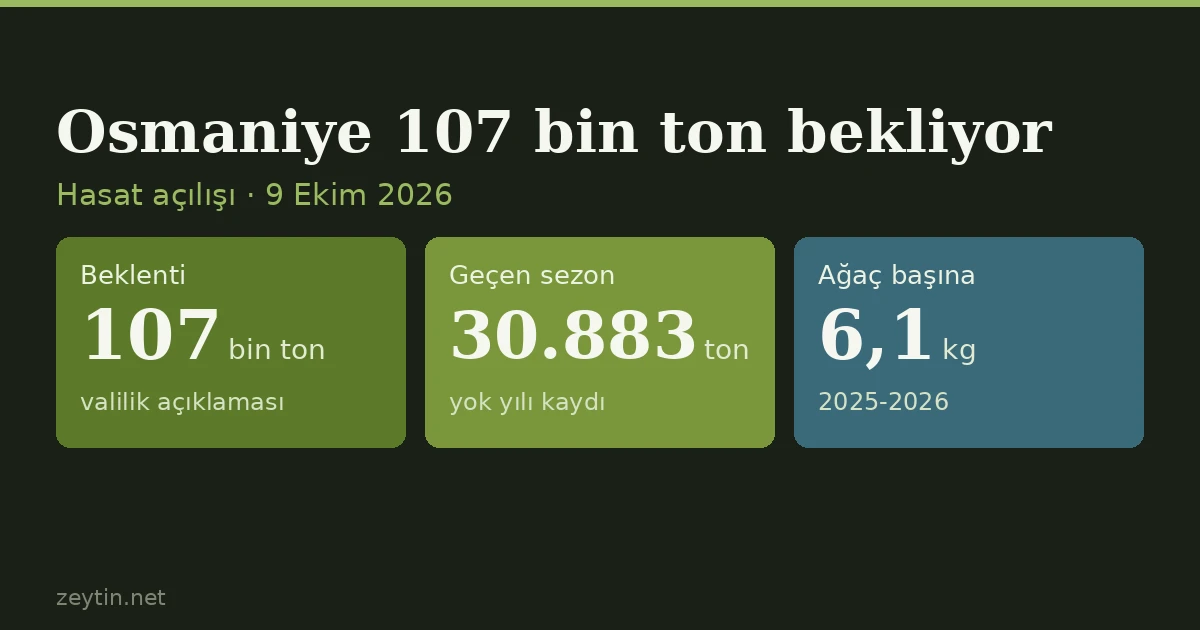
Osmaniye expects 107,000 tonnes: 3.5 times last season, in line with on-year averages
The governor's office in Osmaniye says the province's roughly 10 million olive trees are expected to yield more than 107,000 tonnes this year. That is 3.5 times last season — but 2025-2026 was an off year, and the forecast is consistent with on-year yields. Small discrepancies remain in tree counts and ranking.