Portugal heads back to 177,000 tonnes: output up 10%, farm diesel up 60%
Portugal's olive association Olivum expects production to rise by about 10% in 2026/27 — a return from 160,000 tonnes to the 177,000 of two years ago. The same statement records a 60% rise in the price of agricultural diesel.
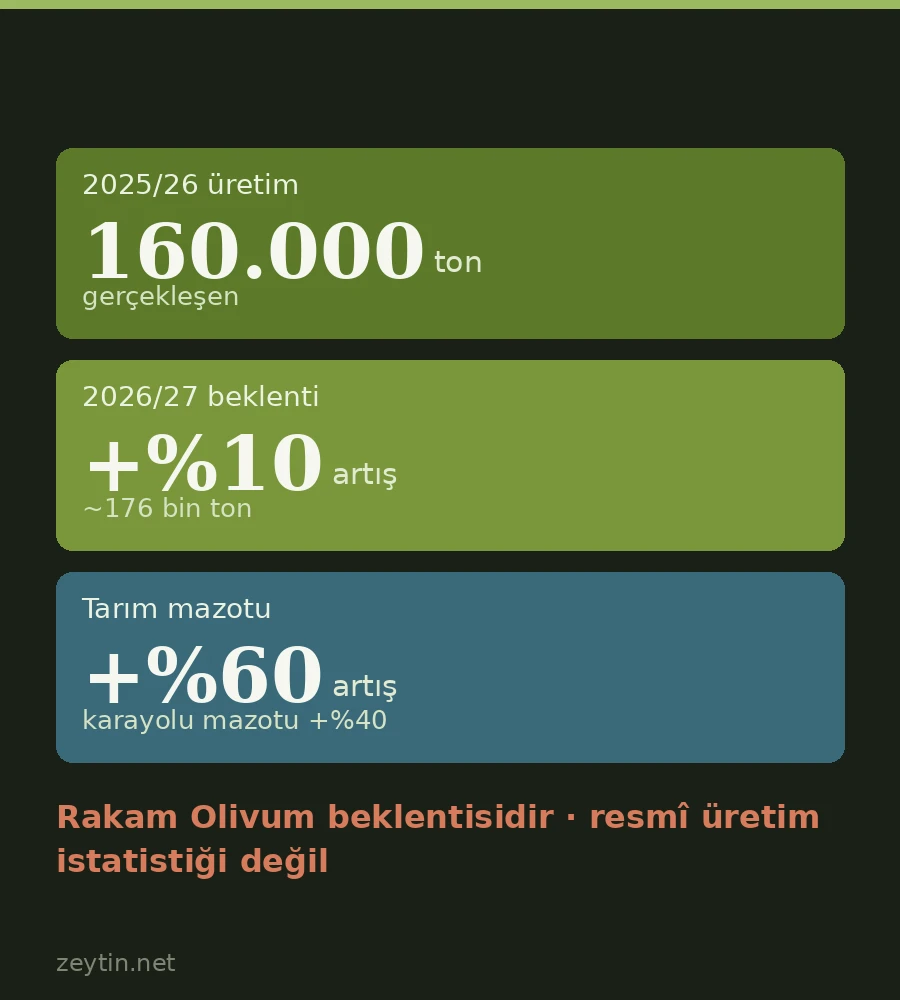
Olivum, the Association of Olive Growers and Olive Oil Mills of Portugal, published its expectation for the 2026/27 season on 23 September: national olive oil production is expected to rise by about 10% against last season.
The number
| Season | Olive oil |
|---|---|
| 2024/25 | ~177,000 t |
| 2025/26 (actual) | 160,000 t |
| 2026/27 (forecast) | +10% |
Ten per cent on top of 160,000 tonnes is 176,000. Olivum's own phrasing — that the season should bring the country "closer to the benchmark figures recorded in the 2024/2025 season" — describes exactly that. What is expected is not a jump but a return to where the country stood two years ago: a recovery, not a record.
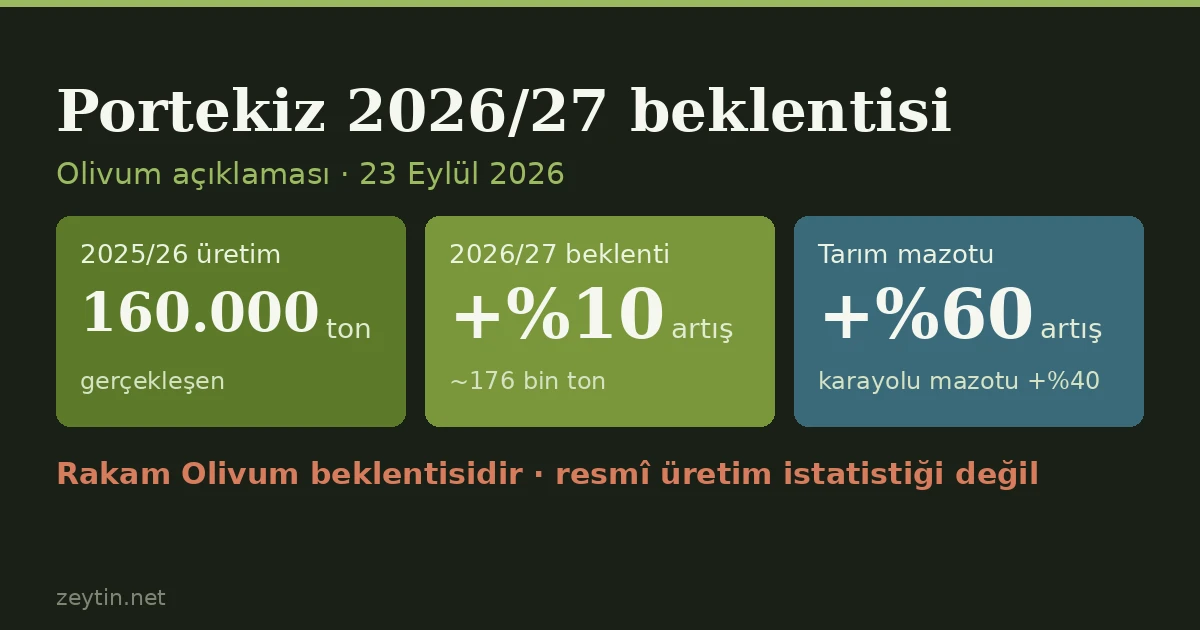
Set the three rows side by side and the amplitude of the swing becomes visible too. The fall from 177,000 to 160,000 tonnes is 9.6%; the expected rise is 10%. Portugal is taking one step back and then a step of the same size forward across two seasons. This is not the large alternate-year swing that olive biennial bearing usually produces — it is a narrower, weather-driven fluctuation. That is the characteristic behaviour of irrigated, densely planted groves: yield falls, but it does not halve.
That distinction matters given the production base Portugal has built over the past two decades. The intensive plantings of the Alentejo made it one of the few countries to redraw the Mediterranean supply map. The difference between its seasons now comes less from the grove expanding than from the weather of the year.
The reason given is heat — but as a calendar effect
Olivum attributes the increase to high temperatures. According to Gonçalo Moreira, a project manager at the association, the heat is accelerating the ripening of the fruit, which could lead some growers to start picking earlier and mills to open earlier in turn.
This deserves a careful reading. Faster ripening primarily shifts the calendar: the harvest is pulled forward and the milling season starts sooner. That it raises tonnage by itself is not self-evident, and the statement does not separately establish the link between the two.
Early harvesting also carries its own well-known trade-off. Fruit picked before full maturity yields less oil, but the oil it yields is higher in polyphenols and aroma. That choice between grade and extraction rate is the same mechanism that makes the price gap between extra virgin and riviera less straightforward than it looks.
The real warning is in costs
In the same statement Olivum says that despite the positive outlook it is watching production costs, particularly fuel. The figures it gives are steep.
| Fuel | Increase (vs. same period last season) |
|---|---|
| Agricultural diesel | ~60% |
| Road diesel | 40% |
Those two lines correspond to two separate cost items in a harvest season: agricultural diesel runs the machinery in the grove, road diesel moves the fruit to the mill and the oil to store. An earlier and more concentrated harvest calendar puts pressure on both at once.
Cost is landing in the same place across the Mediterranean this season. Greece has put its cost per kilo at €3 to €3.5, rising to €5 once labour is counted; in Spain the cost of a traditional grove, €5.31, sits above the selling price. No comparable per-kilo cost has been published for Portugal. What we have is the increase in the fuel line alone.
The Mediterranean supply picture
Portugal's 10% is a small movement on its own. But other lines point the same way this season: Algeria is expecting a record 150,000 tonnes and Syria's crop is doubling. Running the other way, Tunisia is falling from 500,000 tonnes to 300,000.
Added together, this is what we have called the opposite phase in the Mediterranean looks like in its current year: one country's decline is met by another's rise, while the pool itself grows. That is a floor that pulls price expectations down rather than up.
What it means for Türkiye
Portugal's extra 16,000 tonnes does not compete with Türkiye's own harvest; it competes for the same buyers. A large share of Portuguese output moves north in bulk to Italy, and Italy has turned from a production giant into a trade hub that exports more than it makes — so the door that surplus Iberian oil goes through is a known one.
That is part of the picture facing Turkish exporters this season. Olive oil exports were still 62% down in value at the end of August, and the new season opens on expectations of a large crop. When a bulk buyer has more options, the seller has less leverage. Portugal's recovery is not distant news for that reason.
Who is making the statement
Olivum was founded in 2013 and is headquartered in Beja, in the Alentejo. The association represents more than 53,000 hectares of olive groves, 21 mills, and roughly 70% of national olive oil production. The statement therefore covers most of the sector — but a growers' association's expectation is not a measurement by a national statistics office.
Reading it carefully
⚠ The figure is Olivum's expectation, not an official production statistic. The association represents about 70% of national output, not all of it.
⚠ In Moreira's own words, it is "still too early to draw conclusions about the season." We have written separately about when a crop estimate becomes final; the number moves in both directions as picking progresses.
⚠ The link between heat and higher output is not explained. Accelerated ripening brings the harvest calendar forward; why it should raise volume is not argued in the statement.
⚠ The 10% was not given as a tonnage. The 176,000 tonnes in the table is our own arithmetic on 160,000; Olivum gave only the percentage and the reference to 2024/25.
⚠ The fuel increases are given as average prices in mainland Portugal. They describe a national average, not the cost increase of any single operation.
One rating per visitor; you can change yours at any time. Ratings are real reader votes — no seeded or default scores.
Related
 Article
"Jewels of the Adriatic": four countries choose to compete on quality, not volume
Slovenia, Croatia, Bosnia and Herzegovina and Montenegro together produce under 0.5% of the world's olive oil — yet Croatia finished second worldwide at the NYIOOC. A panel in Mostar proposed a shared umbrella brand: origin stays, common rules are the condition.
 Article
Skilled operators for olive mills: training ends in Milas, Muğla trains women operators
Ahead of the harvest, two training programmes in Muğla focus on operators, the most critical link in olive mills. A three-day operator course run by MİTSO, Milas Tariş and HAUS Makine has ended in Milas, and the Muğla Chamber of Commerce and Industry is launching a 50-place "Women's Hands in Industry" programme to train women as mill operators.
 Article
Concordat in Akhisar: a one-year moratorium for Baktat Zeytin
A Turkish commercial court has granted a one-year definitive moratorium to Baktat Zeytin, a table-olive processor in Akhisar. We set out what the ruling means and why it matters for the sector.
 Article
Syria's crop doubles to 954,000 tonnes — and the oil still only feeds itself
Syria's Ministry of Agriculture expects 954,000 tonnes of olives in 2026, up from 412,000 last season. The 101,000 tonnes of oil that implies barely covers domestic consumption — a doubled crop that still produces no export surplus.